Ethiopia’s reinsurance capacity has grown, with institutions like the Ethiopian Insurance Corporation increasing risk-bearing capacity to over 6 trillion Ethiopian birr. Reinsurance provides a crucial safety net for the country’s growing non-life insurance sector, particularly in high-risk areas such as livestock and crop insurance. Yet, critics point out that reinsurance largely serves the general insurance sector, leaving life insurance—a potential growth area—underdeveloped.
By Ayele Addis Ambelu (africaunionmedia@gmail.com)
Ethiopia’s insurance industry, which dates back to 1905, has undergone significant transformations. From its early days covering sea travel and fire accidents to a centralized system under the military regime and now a liberalized yet underperforming sector, the story of Ethiopian insurance is one of resilience, reform, and untapped potential.
Ethiopia’s insurance sector has been linked to the Habesha Bank for over 100 years, influencing modern-day reinsurance strategies. This journey reflects a broader story of Ethiopia’s economic and regulatory transformation.
Historical Context: A Century of Progress and Setbacks
The Ethiopian insurance industry expanded significantly after the first insurance law was enacted in 1962. This period saw 15 companies and 40 agents enter, fueled by partnerships between local and foreign insurers. However, the socialist policies of the military regime in the 1970s nationalized the industry, stifling competition and innovation. The post-1991 liberalization brought private players back, yet the sector’s growth has remained underwhelming compared to its regional counterparts.
A Century-Old Industry Struggling to Modernize
While the sector boasts a history of over 100 years, its contribution to Ethiopia’s GDP remains a mere 0.44%, compared to 2.8% in Kenya and 7% in South Africa. Experts attribute this stagnation to outdated laws, a lack of innovation, and insufficient technological investment.
Ato Tsegaye Kemsi, an industry veteran, notes that restrictive policies have hampered growth. “Our current laws are not fit for purpose. They prevent companies from engaging in short-term investments and offering innovative insurance products,” he says.
Current State of the Industry
Despite having 17 insurance companies today, Ethiopia’s insurance penetration is just 0.44% of GDP—far below Kenya (2.8%) and South Africa (7%). Experts like Ato Tsegaye Kemsi highlight outdated policies and limited investment opportunities as key barriers. “Ethiopia’s insurance laws are restrictive and fail to encourage market innovation,” he argues.
Reinsurance Capacity: A Growing Necessity
Ethiopia’s reinsurance capacity has grown, with institutions like the Ethiopian Insurance Corporation increasing risk-bearing capacity to over 6 trillion birr. Reinsurance provides a crucial safety net for the country’s growing non-life insurance sector, particularly in high-risk areas such as livestock and crop insurance. Yet, critics point out that reinsurance largely serves the general insurance sector, leaving life insurance—a potential growth area—underdeveloped.
A Lifeline for Farmers and Herders
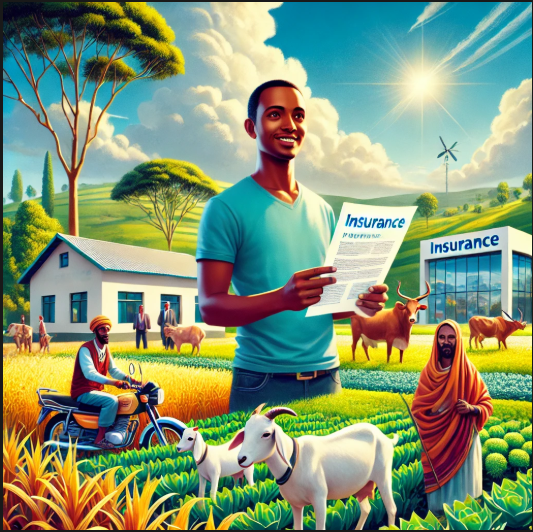
Amid these challenges, innovative programs are making a difference. The Ministry of Agriculture, with World Bank support, has introduced livestock insurance in drought-prone regions. Pastoralists like Sarah Abdi Muse, who lost livestock to drought in the Somali region, are now insuring their herds. “Livestock insurance saved my animals and my livelihood,” she says, her face alight with hope. Over 160,000 pastoralists across Ethiopia have benefited from similar schemes.
In southwestern Ethiopia, Kiyas Shanko shares a similar story. Once unimaginable, his savings account now holds 30,000 birr, thanks to a livestock insurance initiative covering 90% of premiums. “This has not just saved my cattle but also transformed my mindset,” he says.
Innovative Insurance Mechanisms
Ethiopia has introduced indices-based livestock Insurance (IBLI) to protect pastoralists in drought-prone regions. Programs supported by the World Bank and Ministry of Agriculture have benefited over 160,000 pastoralists, offering coverage for up to 90% of premiums. Beneficiaries like Sarah Abdi Muse recount how insurance helped her save livestock during severe droughts, transforming her economic outlook.
Crop insurance schemes have also emerged, aiding farmers in regions like Amhara, where disease and climate risks threaten livelihoods. These programs combine government funding with private-sector participation, showcasing a model for future growth.
Ethiopia’s reinsurance capacity has grown, with institutions like the Ethiopian Insurance Corporation increasing risk-bearing capacity to over 6 trillion birr. Reinsurance provides a crucial safety net for the country’s growing non-life insurance sector, particularly in high-risk areas such as livestock and crop insurance. Yet, critics point out that reinsurance largely serves the general insurance sector, leaving life insurance—a potential growth area—underdeveloped.
Legal Protections and Policy Gaps
Ethiopia’s insurance law, governed by the Commercial Code of 1952 and subsequent proclamations, emphasizes indemnity and good faith. However, many stakeholders criticize its limitations. For instance, companies can invest only 15% of premiums in long-term ventures, curbing their financial growth. Additionally, policies often mirror foreign models, ignoring Ethiopia’s unique socio-economic realities.
Dr. Fikru Regasa, State Minister for Livestock, advocates for a comprehensive policy overhaul. “Our insurance system must be rooted in Ethiopian realities to address current and emerging risks,” he says.
Policy Reforms and Regional Lessons
Ethiopia’s journey offers lessons for the continent. Regional comparisons underscore the need for reform. South Africa’s insurance penetration, driven by life insurance, dwarfs Ethiopia’s, where non-life insurance dominates at 95% of coverage. Experts suggest that Ethiopia’s National Bank should adopt a regulatory framework fostering competition and innovation.
Dr. Fikru Regasa, State Minister for Livestock, emphasizes the importance of policies tailored to Ethiopia’s unique context. “We need to develop insurance products rooted in our realities rather than copying foreign models,” he asserts.
The insurance industry faces several criticisms:
- Limited Innovation: Products remain unchanged for decades, failing to meet evolving consumer needs.
- Overreliance on Motor Insurance: More than 65% of coverage is vehicle-related, overshadowing other critical areas like health and life insurance.
- Lack of Competition: Government-backed companies dominate large projects, stifling market dynamics.
- Regulatory Shortcomings: The National Bank of Ethiopia’s oversight is criticized for being bureaucratic and under-resourced.
Experts propose establishing an independent regulatory commission to supervise and modernize the sector. Ato Tsegaye Kemsi adds, “Without reform, Ethiopia’s insurance industry will continue to lag behind its African peers.”
Future Outlook: Opportunities and Challenges
The Ethiopian government and private sector recognize the untapped potential of rural and microinsurance. Efforts to expand insurance to farmers, pastoralists, and low-income citizens are gaining traction. Meanwhile, initiatives to attract foreign partnerships and leverage technology are under discussion.
However, challenges remain. The sector must overcome low public awareness, limited professional capacity, and restrictive legal frameworks. As the industry moves toward reform, stakeholders must balance short-term gains with long-term sustainability.
Looking Ahead
Despite its struggles, Ethiopia’s insurance sector shows promise. New initiatives, like rural crop and livestock insurance, signal a shift toward inclusivity and resilience. However, realizing its full potential requires a concerted effort from policymakers, private stakeholders, and international partners.
As Ethiopia charts its path forward, the stories of farmers like Sarah and Kiyas remind us of what’s at stake: livelihoods, stability, and the promise of a safety net for all. The question remains: Can Ethiopia’s insurance industry rise to the challenge and become a model for Africa?
Ethiopia’s insurance sector is at a crossroads. Its historical resilience, coupled with emerging innovations like livestock insurance, offers hope. Yet, without bold reforms, its potential will remain unrealized. The stories of farmers and herders saved by insurance during crises serve as a reminder: insurance is not just a financial product—it’s a lifeline. The question is whether Ethiopia can rise to the challenge and set a new benchmark for Africa.